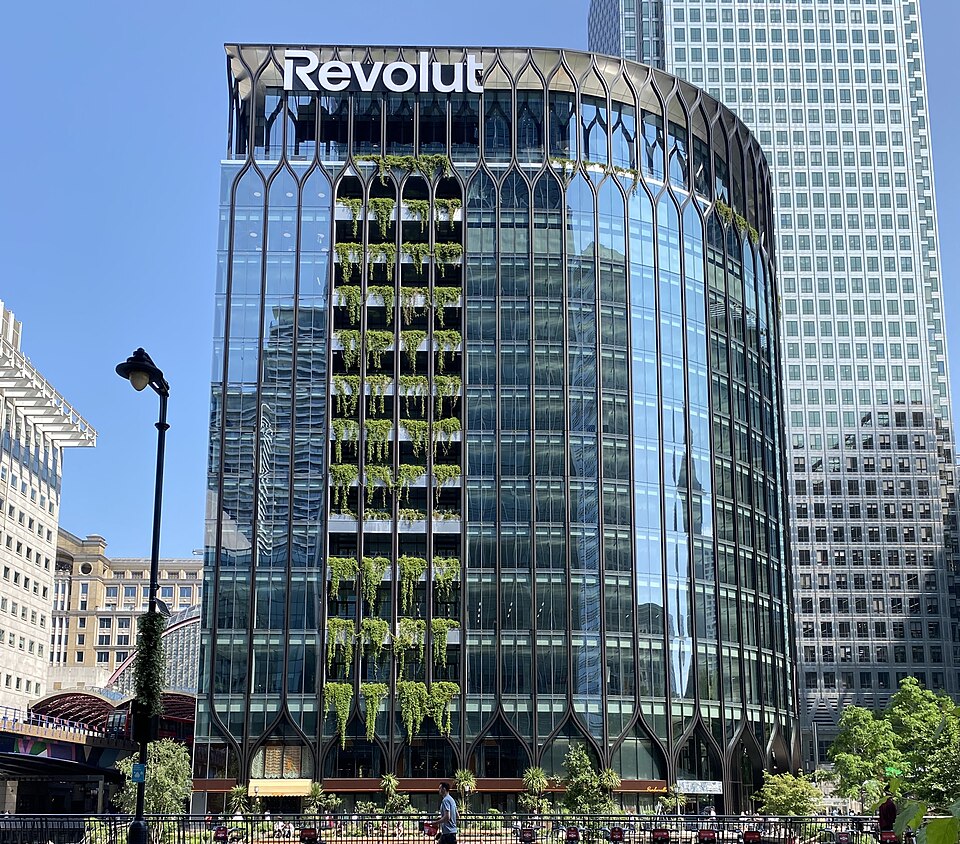
Revolut has evolved from a small fintech startup offering cheaper foreign exchange services into Europe's most valuable privately held technology company, with a valuation of $115 billion.
Founded just over a decade ago, the London-based digital bank is now challenging established financial institutions across international markets.
However, despite its rapid expansion and growing customer base, Revolut still faces significant obstacles, including relatively low revenue per customer and a lending business considerably smaller than those of traditional banks.
Chief Executive Nik Storonsky has ambitious plans to make Revolut a global banking powerhouse, expanding into markets such as Mexico and Australia. The company has recently secured several new licences as it seeks to establish retail operations across multiple continents.
Its valuation now exceeds that of major European lenders, including Britain's Barclays and France's Societe Generale. Revolut reported £1.7 billion in pre-tax profits in 2025, compared with Barclays' £9 billion, although its growth is attracting increasing attention from banking executives.
Cihan Duran, a director at S&P Global Ratings, said European bank leaders increasingly view Revolut as a major competitor because of its aggressive marketing and rapid expansion.
Nevertheless, international growth brings challenges. In the United States, where Revolut holds a provisional licence, the company will face intense competition from established financial institutions.
The fintech has also encountered regulatory and security problems, including a fine in Lithuania over anti-money laundering shortcomings and a September incident in which hackers impersonating government investigators obtained customer information. Revolut said customer funds and systems were unaffected.
Customer numbers remain one of its strongest advantages. Revolut reports approximately 80 million users worldwide, approaching JPMorgan's 84 million and significantly exceeding HSBC's 41 million. In Ireland, the company says 80% of adults have a Revolut account.
However, its financial performance reveals a significant gap with traditional lenders. At the end of 2025, Revolut had just £2.2 billion in loans, representing a loan-to-deposit ratio of 6%, compared with 55% for HSBC and 86% for Societe Generale.
Expanding lending could increase revenue but would expose Revolut to additional credit risks and fierce competition in mortgage markets.
Another priority is persuading customers to use Revolut as their main bank rather than a secondary account for payments and currency exchange. The company reported a 45% annual increase in primary-account users but did not disclose the total number.
Investors are closely monitoring this development, alongside customer deposit growth, as indicators of the company's long-term potential.
Revolut's next challenge will be converting its enormous customer base and impressive valuation into sustainable banking revenues while competing with established financial institutions worldwide. Photo by Boubloub, Wikimedia commons.